We would like to inform you about a significant revision by Japan Customs clarifying the definition of an importer. This change took effect on October 1, 2023.
Following the revision, there has been an increase in cases where foreign corporations must appoint an Attorney for Customs Procedures (ACP), also known as a Customs Procedure Agent or CPA, and become the Importer of Record (IOR) themselves. Merely designating another entity as the importer in name only is no longer considered acceptable under Japanese customs rules.
In instances other than normal import transactions between an overseas seller and a Japanese buyer, where the importer does not have the authority to dispose of the goods after importation (for example, when a foreign corporation does not become the IOR themselves and nominates a forwarder, customs broker, or another third party who is not involved in the transaction to be the nominal IOR), there is a high probability that approval will not be granted as such nominations are not recognized as legitimate importers, therefore careful attention is required.
As a professional ACP firm, we follow the law to facilitate proper import procedures. You can entrust us with your importation needs with confidence. We look forward to discussing further with you.
Japan Customs’ Official Guideline for E-Commerce Sellers
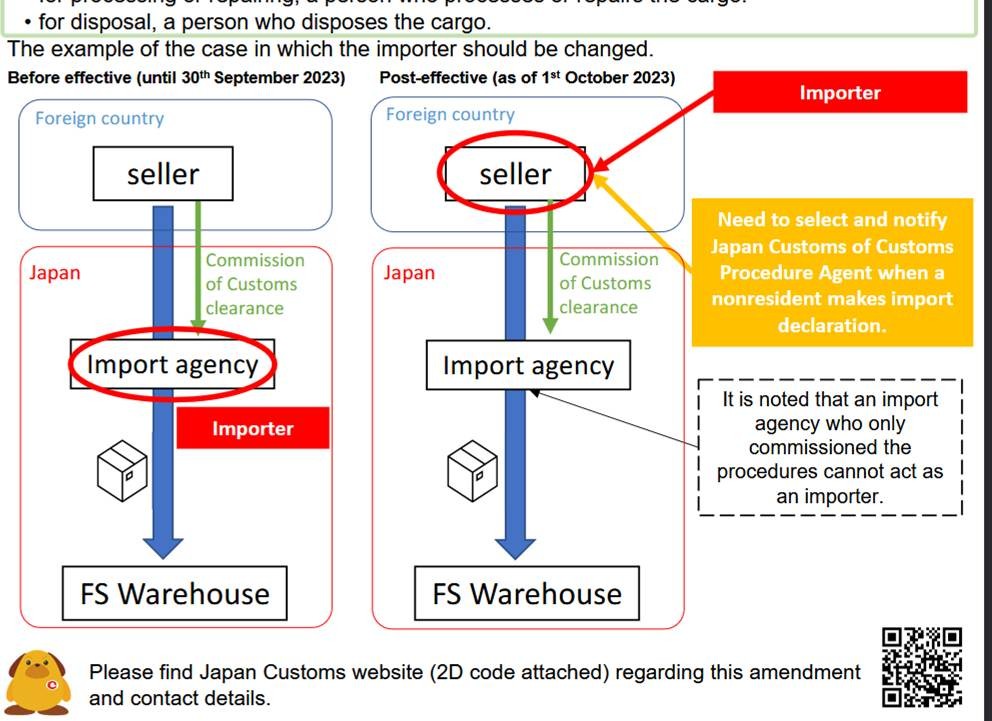
Here is the official guideline from Japan Customs. On page 2 of the leaflet, you’ll see a clear comparison:
- On the left side, which reflects the rule before September 30, 2023, it was allowed for an “Import Agency” (such as a logistics or warehouse company) to act as the Importer of Record (IOR).
- On the right side, from October 2023 onward, the Seller must be the IOR by appointing a Customs Procedures Agent — which is what we refer to as an ACP (Attorney for Customs Procedures).
- Japan Customs: Revision of Import Declaration Items and Attorney for Customs Procedure (ACP) System
- Japan Customs Notice – Available in English, Chinese, Korean, and Japanese
Revisions Effective October 1, 2023:
Definition of the Importer
Under Japan Customs practice, the importer is determined as follows.
For cargo imported under an import transaction, such as a normal transaction between an overseas seller and a buyer in Japan, the importer is the buyer in Japan, namely the person who imports the cargo as referred to in Article 6-1(1) of the General Notification of the Customs Act.
In cases other than the above, the importer is the person who has the right to dispose of the import cargo at the time of import declaration.
In addition, another person acting for the purpose of the import, such as those listed below, may also be treated as the importer:
- for cargo imported under a lease contract, the person who rents and uses the cargo;
- for cargo imported for consignment sales, the trustee who sells the cargo in their own name under the consignment arrangement;
- for cargo imported for processing or repair, the person who processes or repairs the cargo; and
- for cargo imported for disposal, the person who disposes of the cargo.
Importer Defined as the “Person Having the Right of Disposal”
One of the most notable aspects of the amendment is the clarification that the “person having the right of disposal” is regarded as the importer under Japan Customs law. The term “right of disposal” is similar to ownership, but not identical. Although there is no explicit definition in the customs-related legislation, according to Japan Customs, it refers to the authority to decide how the goods will be handled after being released into Japan—for example, whether to sell the goods or to enter into a sales contract.
For additional information, please refer to the following resources:
- Japan Customs: Importer Eligibility and ACP System — English Leaflet
- English: Announcement from Japan Customs | Mandatory to Use ACP in Many Cases – Attorney for Customs Procedure
Case Study: Directives to use ACP
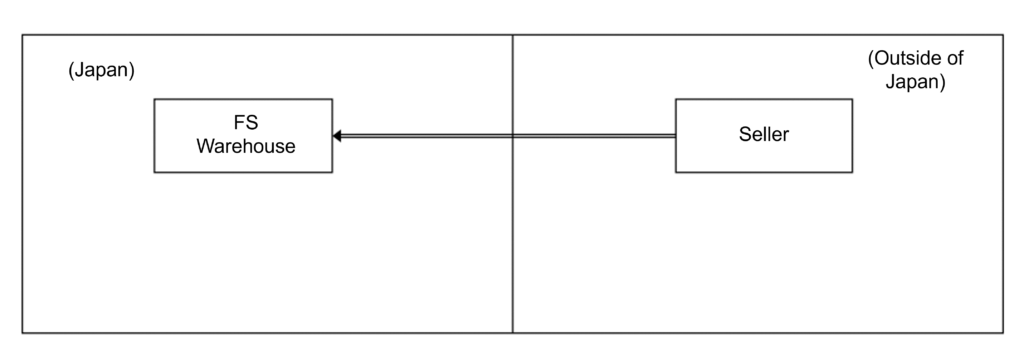
Case 1: Importing Goods Using FS (Fulfillment Services) by Non-resident Sellers
A non-resident seller plans to import goods for sale domestically using FS provided by EC platform operators. At the time of import declaration, there is no sales contract between the seller and the consumer. The seller (non-resident) is the main entity for sales on the EC platform after domestic pickup of the goods. Therefore, the seller, who aims to sell the goods in accordance with the purpose of import, needs to become the import declarant and appoint Attorney for Customs Procedure (ACP) to carry out the import declaration.
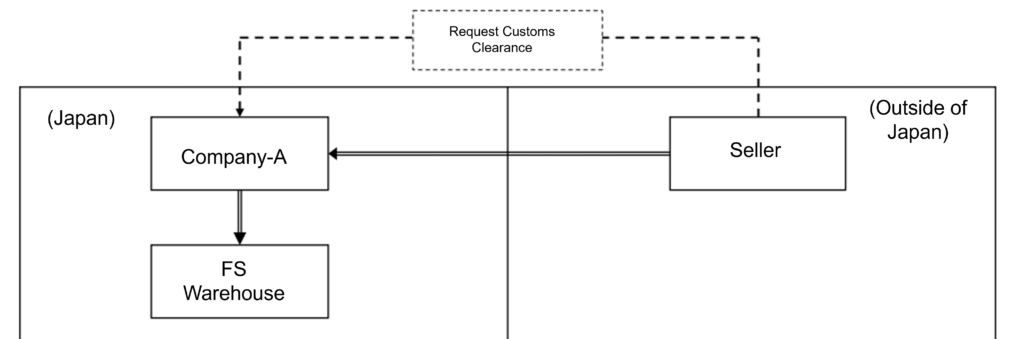
Case 2: Importing Goods Using FS by Non-resident Sellers
A non-resident seller plans to import goods for sale domestically using FS provided by EC platform operators. At the time of import declaration, there is no sales contract between the seller and the consumer. The seller (non-resident) entrusts domestic customs clearance arrangements to Company-A (located in Japan), but the main entity for selling the goods within the domestic market using FS remains the seller (non-resident). It is planned that the seller (non-resident), who intends to sell the goods on the EC platform after domestic pickup, should become the import declarant and appoints Attorney for Customs Procedure (ACP) in accordance with the purpose of import declaration.
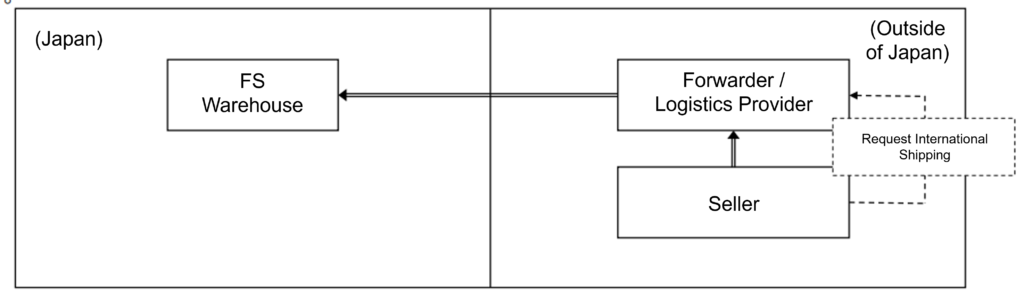
Case 3: Importing Goods Using FS by Non-resident Sellers
A non-resident seller plans to import goods for sale domestically using FS provided by EC platform operators. At the time of import declaration, there is no sales contract between the seller and the consumer. The seller (non-resident) entrusts the transportation of the goods from overseas sellers to Japan to an overseas forwarder, but the main entity for selling the goods within the domestic market using FS remains the seller (non-resident). It is planned that the seller (non-resident), who intends to sell the goods on the EC platform after domestic pickup, will become the import declarant and appoints Attorney for Customs Procedure (ACP) in accordance with the purpose of import declaration.
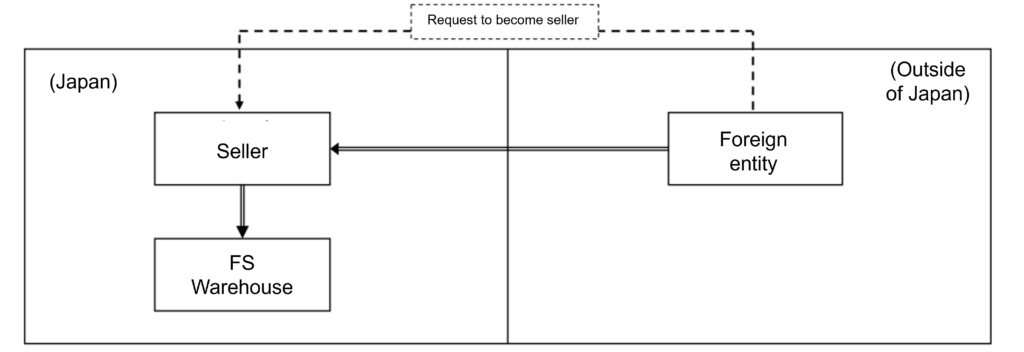
Case 4: Importing Goods for Consignment Sales
Goods (consignment sales goods) intended for domestic sale by an assignee who has received consignment sales from a non-resident consignor are imported. The imported goods are stored in an FS warehouse and sold on the EC platform under the name of the assignee. The assignee is the main entity for selling the goods within the domestic market using FS.
Either of the following options is necessary:
The consignor (non-resident) who has the authority to dispose of the consignment sales goods becomes the import declarant, appoints Attorney for Customs Procedure (ACP), and carries out the import declaration.
The assignee (i.e., the seller on the EC platform) who conducts the act of selling on behalf of themselves as the purpose of import becomes the import declarant and carries out the import declaration.
Track Record – Attorney for Customs Procedures (ACP) Services
We have supported import and export operations in Japan for over 300 clients across more than 40 countries.
